
How to Finance a Moped Online – Step-by-Step Guide
If you’re considering buying a moped but don’t want to pay the full price upfront, learning how to finance a moped online can save you time, money, and stress.
Whether you’re a student, daily commuter, delivery rider, or simply looking for a fuel-efficient ride, online moped financing has become faster, simpler, and more accessible than ever. In many cases, you can apply, get approved, and sign documents — all without stepping into a dealership.
This in-depth guide walks you through:
-
What moped financing really means
-
How online financing works
-
Step-by-step approval process
-
Credit score requirements
-
Interest rates & hidden costs
-
Best lenders & comparison tips
-
Risks and smart strategies
-
FAQs (schema-ready)
Let’s start with the basics.
What Does It Mean to Finance a Moped Online?
Financing a moped online means borrowing money from a lender (bank, credit union, fintech company, or dealership partner) through a digital platform to purchase your moped, then repaying it in monthly installments with interest.
Instead of paying $1,500–$4,000 upfront, you:
-
Apply online
-
Get approved
-
Make a down payment (sometimes optional)
-
Pay monthly installments
It’s similar to auto financing — just scaled down.
Why More People Are Financing Mopeds in 2026
Mopeds and scooters are surging in popularity due to:
-
Rising fuel prices
-
Urban traffic congestion
-
Gig economy jobs (Uber Eats, DoorDash, etc.)
-
Affordable insurance
-
Eco-friendly electric options
According to the International Energy Agency, two-wheelers account for over 30% of motor vehicle fleets globally. Financing makes ownership more accessible.
How to Finance a Moped Online: Step-by-Step Process
Here’s the exact roadmap professionals recommend.
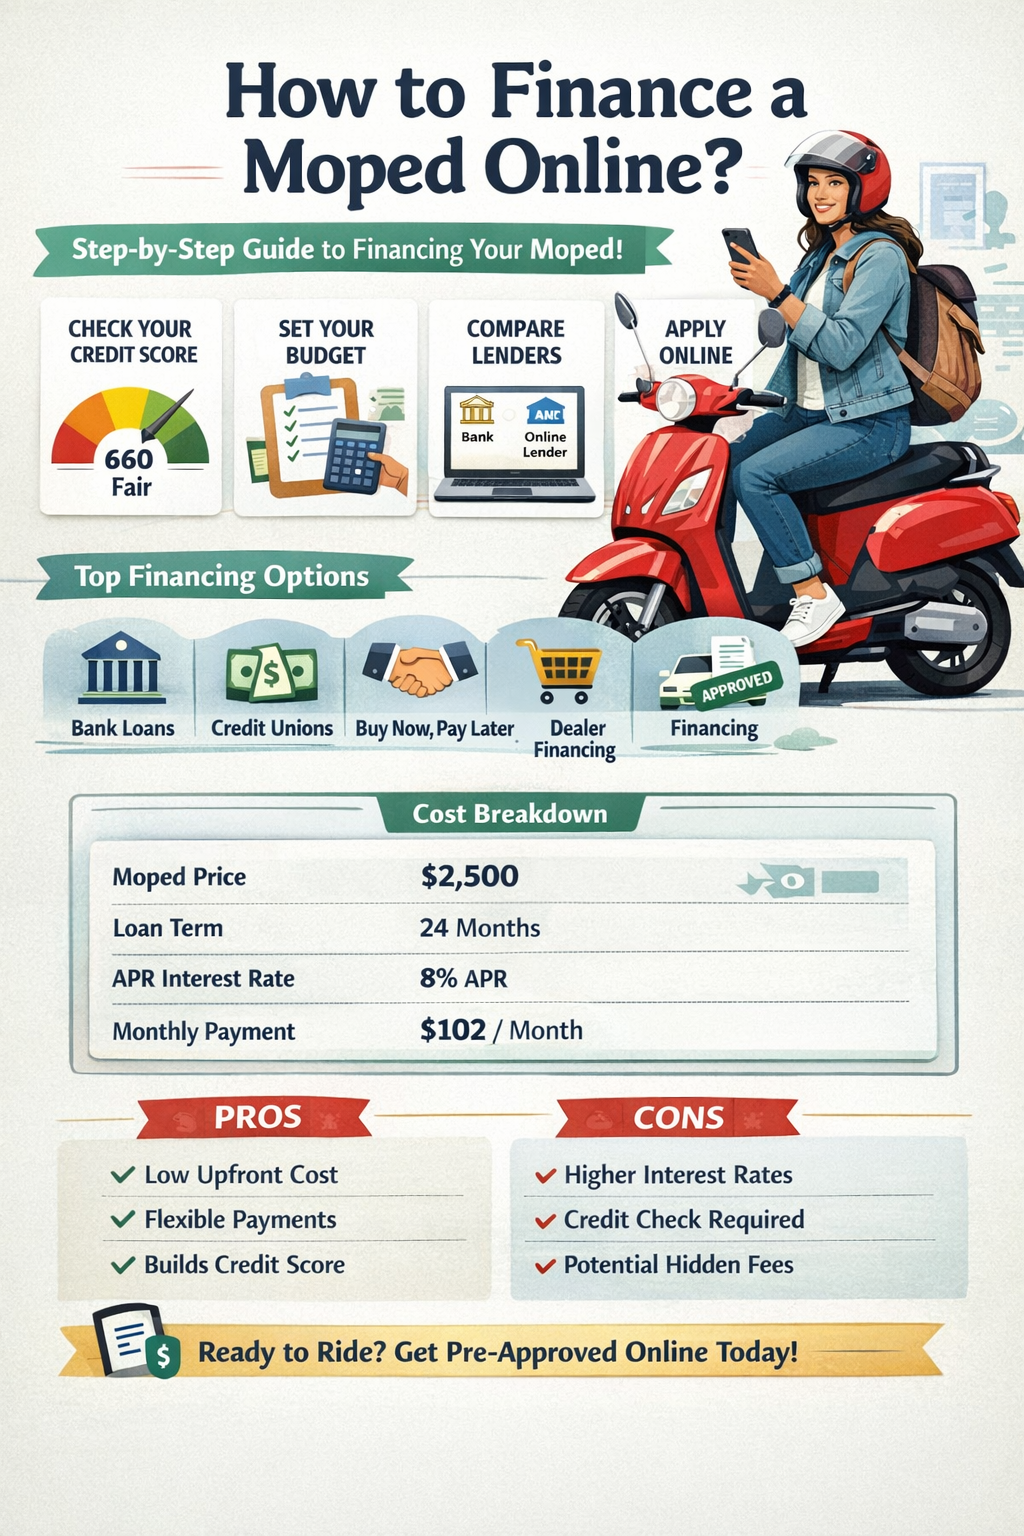
Step 1: Determine Your Budget
Before applying, calculate:
-
Purchase price of moped
-
Down payment (0–20%)
-
Monthly payment you can afford
-
Insurance cost
-
Registration fees
-
Maintenance
Example Budget Breakdown
| Item | Estimated Cost |
|---|---|
| Moped price | $2,500 |
| Down payment (10%) | $250 |
| Loan amount | $2,250 |
| Interest (8% APR, 24 months) | ~$200 total |
| Monthly payment | ~$102 |
Pro Tip: Keep your monthly payment under 15% of your monthly income.
Step 2: Check Your Credit Score
Your credit score directly impacts:
-
Loan approval chances
-
Interest rate
-
Required down payment
Credit Score Ranges & What They Mean
| Credit Score | Loan Chances | Expected APR |
|---|---|---|
| 720+ | Excellent | 5–8% |
| 660–719 | Good | 8–12% |
| 600–659 | Fair | 12–18% |
| Below 600 | Difficult | 18–30% |
You can check your credit via major bureaus like:
-
Experian
-
Equifax
-
TransUnion
Improving your credit before applying can save hundreds in interest.
Step 3: Compare Online Financing Options
There are 4 primary ways to finance a moped online:
1. Bank Personal Loans
Best for: Good credit borrowers
Pros:
-
Lower interest rates
-
Fixed payments
-
No vehicle collateral needed
Cons:
-
Strict credit requirements
2. Credit Unions
Often offer better rates than traditional banks.
Pros:
-
Lower APR
-
Flexible approval
-
Member benefits
Cons:
-
Must qualify for membership
3. Buy Now, Pay Later (BNPL) Financing
Some online retailers offer installment options.
Pros:
-
Fast approval
-
Minimal paperwork
Cons:
-
Higher fees if missed payments
4. Dealership Online Financing
Many dealerships offer online applications.
Pros:
-
Convenience
-
One-stop purchase
-
Promotional rates
Cons:
-
May have higher markups
Step 4: Pre-Qualification (Soft Credit Check)
Most reputable lenders allow prequalification.
Benefits:
-
No hard credit inquiry
-
See estimated APR
-
Compare offers safely
Never skip this step.
Step 5: Submit Full Application
You’ll need:
-
Government ID
-
Proof of income
-
Bank statements
-
Social Security Number (or national ID)
-
Address proof
Approval can take:
-
5 minutes (fintech lenders)
-
1–2 days (banks)
-
Same day (dealerships)
Step 6: Review Loan Terms Carefully
Before signing, check:
-
APR (Annual Percentage Rate)
-
Loan term length
-
Total repayment amount
-
Early repayment penalties
-
Late fees
-
Insurance requirements
Step 7: Sign & Receive Funds
Depending on lender:
-
Funds sent to you
-
Funds sent directly to dealer
-
Instant digital contract signing
Once funded — your moped is yours.
How Much Does It Cost to Finance a Moped?
The total cost depends on:
-
Purchase price
-
APR
-
Loan term
-
Down payment
Example Comparison
| Loan Term | APR | Monthly Payment | Total Paid |
|---|---|---|---|
| 12 months | 7% | $216 | $2,592 |
| 24 months | 10% | $115 | $2,760 |
| 36 months | 14% | $86 | $3,096 |
Longer terms = lower monthly payments but higher total cost.
Can You Finance a Moped with Bad Credit?
Yes — but expect:
-
Higher interest rates
-
Larger down payment
-
Shorter loan terms
Ways to Improve Approval Chances
-
Add a co-signer
-
Increase down payment
-
Choose cheaper model
-
Improve credit utilization
-
Show stable income
Some lenders specialize in subprime borrowers.
Electric Moped Financing: What’s Different?
Electric mopeds often qualify for:
-
Government incentives
-
Tax credits
-
Green financing programs
Check your local energy authority website.
Benefits:
-
Lower operating cost
-
Reduced maintenance
-
Environmental benefits
Pros and Cons of Financing a Moped Online
Pros
-
Instant approvals
-
Competitive rates
-
Compare multiple lenders
-
No dealership pressure
-
Convenience
Cons
-
Risk of hidden fees
-
Higher interest if poor credit
-
Online scams (must verify lenders)
Online Moped Financing vs Paying Cash
| Factor | Financing | Paying Cash |
|---|---|---|
| Upfront Cost | Low | High |
| Interest | Yes | No |
| Ownership | After repayment | Immediate |
| Credit Impact | Builds credit | None |
If you have savings but want liquidity — financing can preserve cash flow.
Common Mistakes to Avoid
-
Skipping prequalification
-
Ignoring APR vs interest rate difference
-
Choosing longest term blindly
-
Not checking lender reputation
-
Missing insurance requirement
How to Get the Lowest Interest Rate
-
Improve credit score above 700
-
Make 15–20% down payment
-
Choose shorter loan term
-
Compare at least 3 lenders
-
Avoid dealership markups
-
Apply during promotional periods
Real-World Example
Ali, a university student, wanted a $2,000 moped.
-
Credit score: 680
-
Down payment: $300
-
Loan term: 24 months
-
APR: 9%
His monthly payment was $77.
He used prequalification to compare three lenders and saved $340 in total interest by choosing the lowest APR.
Is Financing a Moped Worth It?
It makes sense if:
-
You need transportation immediately
-
You don’t want to drain savings
-
You qualify for reasonable APR
-
Monthly payments fit your budget
It may not make sense if:
-
Interest rate exceeds 20%
-
You can comfortably pay cash
-
You’re already in high debt
Frequently Asked Questions (FAQ)
How long does it take to finance a moped online?
Most online lenders provide instant pre-approval within minutes, with full funding in 1–2 business days.
What credit score is needed to finance a moped?
A credit score above 660 improves approval chances, but some lenders approve borrowers with scores below 600 at higher interest rates.
Can I finance a used moped online?
Yes. Many lenders allow used vehicle financing, but rates may be slightly higher than for new mopeds.
Is a down payment required?
Not always. However, putting 10–20% down reduces your interest rate and monthly payment.
Does financing a moped build credit?
Yes. On-time payments are reported to credit bureaus and can improve your credit score.
Expert Tips Most Articles Don’t Tell You
-
Small loans sometimes have higher APR because lenders earn less profit
-
Some lenders charge origination fees (1–5%)
-
Always check if loan is secured or unsecured
-
Gap insurance may not be necessary for low-cost mopeds
-
Insurance may be mandatory before loan disbursement
Final Thoughts: Should You Finance a Moped Online?
Financing a moped online is no longer complicated. With the right preparation, you can secure approval quickly and ride away without draining your savings.
Here’s the smart approach:
-
Check your credit
-
Compare at least three lenders
-
Prequalify first
-
Read terms carefully
-
Keep monthly payments affordable
A moped is one of the most cost-efficient transportation options available today. When financed responsibly, it can be a financially smart decision — not a burden.
If you approach the process strategically, online moped financing can be fast, safe, and surprisingly affordable.