
How Long Can You Finance a Boat?
Short answer:
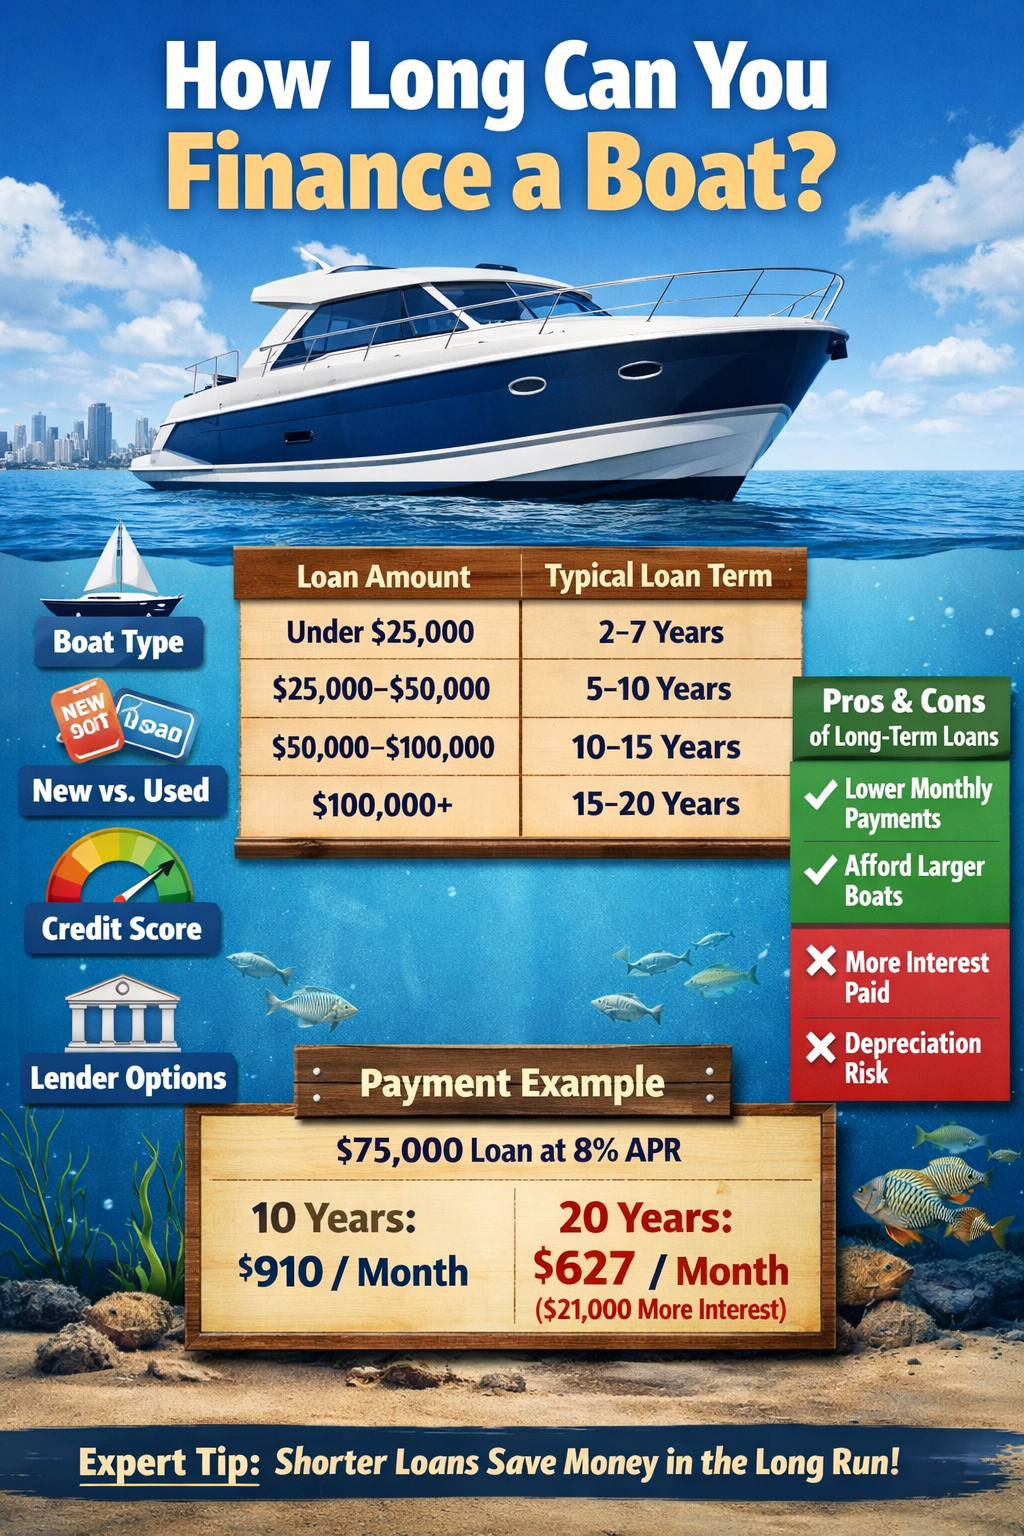
You can typically finance a boat for 2 to 20 years, depending on the loan size and lender.
Here’s a quick breakdown:
| Loan Amount | Typical Loan Term |
|---|---|
| Under $25,000 | 2–7 years |
| $25,000–$50,000 | 5–10 years |
| $50,000–$100,000 | 10–15 years |
| $100,000+ | 15–20 years |
Some marine lenders even offer 20-year boat loans for high-value yachts.
But should you finance that long?
Let’s go deeper.
What Determines How Long You Can Finance a Boat?
Several key factors influence boat financing terms.
1. Loan Amount
The larger the loan, the longer lenders are willing to stretch repayment.
For example:
-
A $15,000 fishing boat → likely 5–7 years
-
A $300,000 yacht → possibly 20 years
Longer terms help keep monthly payments manageable.
2. Type of Boat
Different boats qualify for different loan structures:
-
Pontoon boats
-
Fishing boats
-
Ski boats
-
Sailboats
-
Cabin cruisers
-
Yachts
Luxury vessels are often financed similarly to mortgages.
3. New vs. Used Boat
-
New boats usually qualify for longer financing.
-
Used boats may have shorter maximum terms due to depreciation.
Many lenders limit financing if the boat will be over 20–25 years old at the end of the loan.
4. Credit Score
Your credit score directly impacts both:
-
Loan approval
-
Maximum loan term
Strong credit (700+) = better rates and longer terms.
Lower credit = shorter term and higher interest.
5. Lender Type
Common boat lenders include:
-
Banks
-
Credit unions
-
Marine finance companies
-
Dealership financing programs
For example, lenders like LightStream and BoatUS specialize in boat loans with flexible terms.
Each lender has different underwriting standards.
Typical Boat Loan Terms Explained
Let’s break down what different financing lengths really mean.
2–5 Year Boat Loan
Best for: Smaller boats or buyers who want to minimize interest.
Pros:
-
Less interest paid overall
-
Faster equity buildup
-
Boat paid off quickly
Cons:
-
Higher monthly payments
Example:
$30,000 boat at 7% APR
-
5 years → ~$594/month
-
Total interest ≈ $5,600
7–10 Year Boat Loan
Best for: Mid-range buyers wanting balanced payments.
This is the most common range.
Pros:
-
Manageable payments
-
Moderate interest costs
-
Good balance of flexibility
Cons:
-
More total interest than short-term loans
12–15 Year Boat Loan
Often used for boats priced above $75,000.
Pros:
-
Lower monthly payments
-
Makes larger boats affordable
Cons:
-
Higher lifetime interest
-
Slower equity growth
20-Year Boat Financing
Yes — 20-year terms exist.
Primarily for:
-
Luxury boats
-
Large yachts
-
High-end sailboats
Why lenders allow it:
Boats priced at $250,000+ need extended amortization to keep payments reasonable.
However, this significantly increases total interest paid.
Featured Snippet: Maximum Boat Loan Term
Maximum boat financing terms can extend up to 20 years for high-value boats, while smaller boats typically qualify for 5–10 year loans.
How Boat Financing Compares to Auto Loans
| Feature | Boat Loan | Car Loan |
|---|---|---|
| Typical Term | 2–20 years | 3–7 years |
| Collateral | Boat | Vehicle |
| Depreciation | High | High |
| Insurance Required | Yes | Yes |
Boat loans often run longer than car loans because boats can be very expensive.
Interest Rates on Boat Loans (2026)
Rates vary depending on:
-
Credit score
-
Loan size
-
Term length
-
Market conditions
Most boat loan rates are influenced by broader trends from institutions like the Federal Reserve.
Current typical range:
-
Excellent credit: 6–8%
-
Average credit: 8–12%
-
Subprime: 12%+
Longer terms often carry slightly higher rates.
Should You Finance a Boat for 20 Years?
This is where experience matters.
As someone who has analyzed marine loans for years, here’s the honest truth:
Long Terms Make Boats “Look” Affordable
A $200,000 boat at:
-
10 years → $2,400/month
-
20 years → ~$1,550/month
The payment drops significantly.
But total interest paid nearly doubles.
The Risk of Long Boat Loans
Boats depreciate quickly, especially in the first 5 years.
With long financing:
-
You may owe more than the boat’s value.
-
Selling early could require paying the balance difference.
This is called being “upside down.”
Real-World Financing Example
Let’s compare.
Boat price: $100,000
Down payment: $10,000
Loan: $90,000
APR: 8%
| Term | Monthly Payment | Total Interest |
|---|---|---|
| 7 years | ~$1,402 | ~$27,800 |
| 10 years | ~$1,091 | ~$40,900 |
| 15 years | ~$861 | ~$65,000 |
| 20 years | ~$753 | ~$90,000 |
Notice something?
The 20-year option costs over $60,000 more in interest than the 7-year option.
How to Choose the Right Boat Loan Term
Here’s the professional approach I recommend.
Step 1: Determine True Budget
Don’t just look at monthly payment.
Factor in:
-
Insurance
-
Docking fees
-
Maintenance
-
Fuel
-
Storage
-
Winterization
Boat ownership costs can equal 10% of boat value annually.
Step 2: Aim for 10–15% Down Payment
This reduces:
-
Monthly payments
-
Risk of negative equity
-
Total interest
Step 3: Keep Loan Term Shorter Than Boat Ownership Plan
If you plan to keep the boat 5–7 years:
Don’t take a 20-year loan.
Step 4: Compare Multiple Lenders
Check:
-
Banks
-
Credit unions
-
Online lenders
-
Marine finance specialists
Always compare APR — not just monthly payment.
When Longer Boat Financing Makes Sense
There are cases where extended terms are strategic.
1. Cash Flow Flexibility
If you’re investing money elsewhere at higher returns, a longer loan can preserve liquidity.
2. Tax Strategy (For Some Buyers)
If your boat qualifies as a second home (with sleeping, cooking, and toilet facilities), interest may be deductible. Consult a CPA.
Advanced Strategy: Refinance Later
Some buyers choose:
-
Start with 15–20 year term
-
Make extra principal payments
-
Refinance if rates drop
Refinancing can shorten the loan without initial payment pressure.
What Lenders Look for in Boat Financing
Underwriting criteria typically include:
-
Credit score
-
Debt-to-income ratio
-
Employment stability
-
Down payment amount
-
Boat age and condition
Marine lenders often require a marine survey for used boats over certain values.
Boat Loan vs Personal Loan
Some lenders offer unsecured personal loans for boats.
Secured Boat Loan:
-
Lower rate
-
Longer term
-
Boat used as collateral
Personal Loan:
-
Higher rate
-
Shorter term
-
No collateral
For boats over $25,000, secured loans are usually better.
FAQs: How Long Can You Finance a Boat?
How long can you finance a used boat?
Most lenders offer 5–15 years for used boats, depending on age and condition.
What is the maximum boat loan term?
The maximum term is typically 20 years for large or high-value boats.
Is a 20-year boat loan a bad idea?
It depends. While payments are lower, total interest is significantly higher and depreciation risk increases.
What credit score do you need to finance a boat?
Most lenders prefer 680+, but excellent rates are reserved for 720+ credit scores.
Can you pay off a boat loan early?
Most boat loans have no prepayment penalties, but always confirm with your lender.
Expert Takeaways: What Most Buyers Get Wrong
After reviewing thousands of financing scenarios, here are common mistakes:
-
Focusing only on monthly payment
-
Ignoring depreciation
-
Financing without a down payment
-
Choosing longest term by default
-
Not budgeting for maintenance
A boat is a lifestyle purchase — not just a financial one.
Make decisions accordingly.
Final Thoughts: How Long Should YOU Finance a Boat?
So, how long can you finance a boat?
Technically: up to 20 years.
Strategically: as short as comfortably possible.
The smartest approach is:
-
Put at least 10–20% down
-
Choose a 7–15 year term for most boats
-
Avoid stretching to 20 years unless necessary
-
Compare lenders carefully
-
Consider total cost, not just payment
A boat should bring freedom — not financial stress.
If you structure your financing wisely, you’ll enjoy the water without worrying about the loan.