
1. Introduction: Why HVAC Financing Matters
Replacing an HVAC system is rarely planned.
Most homeowners discover the problem on the hottest day of summer or the coldest night of winter—when the system suddenly fails. Then comes the shock:
“You need a new HVAC system… and it’ll cost thousands.”
That’s where HVAC financing becomes a lifesaver.
If you’re asking can you finance a new HVAC system, you’re not alone. Millions of homeowners rely on financing every year to restore comfort without draining savings.
This guide walks you through every option, cost, benefit, and risk, from beginner to professional level.
2. Can You Finance a New HVAC System? (Short Answer)
Yes — you can finance a new HVAC system in multiple ways.
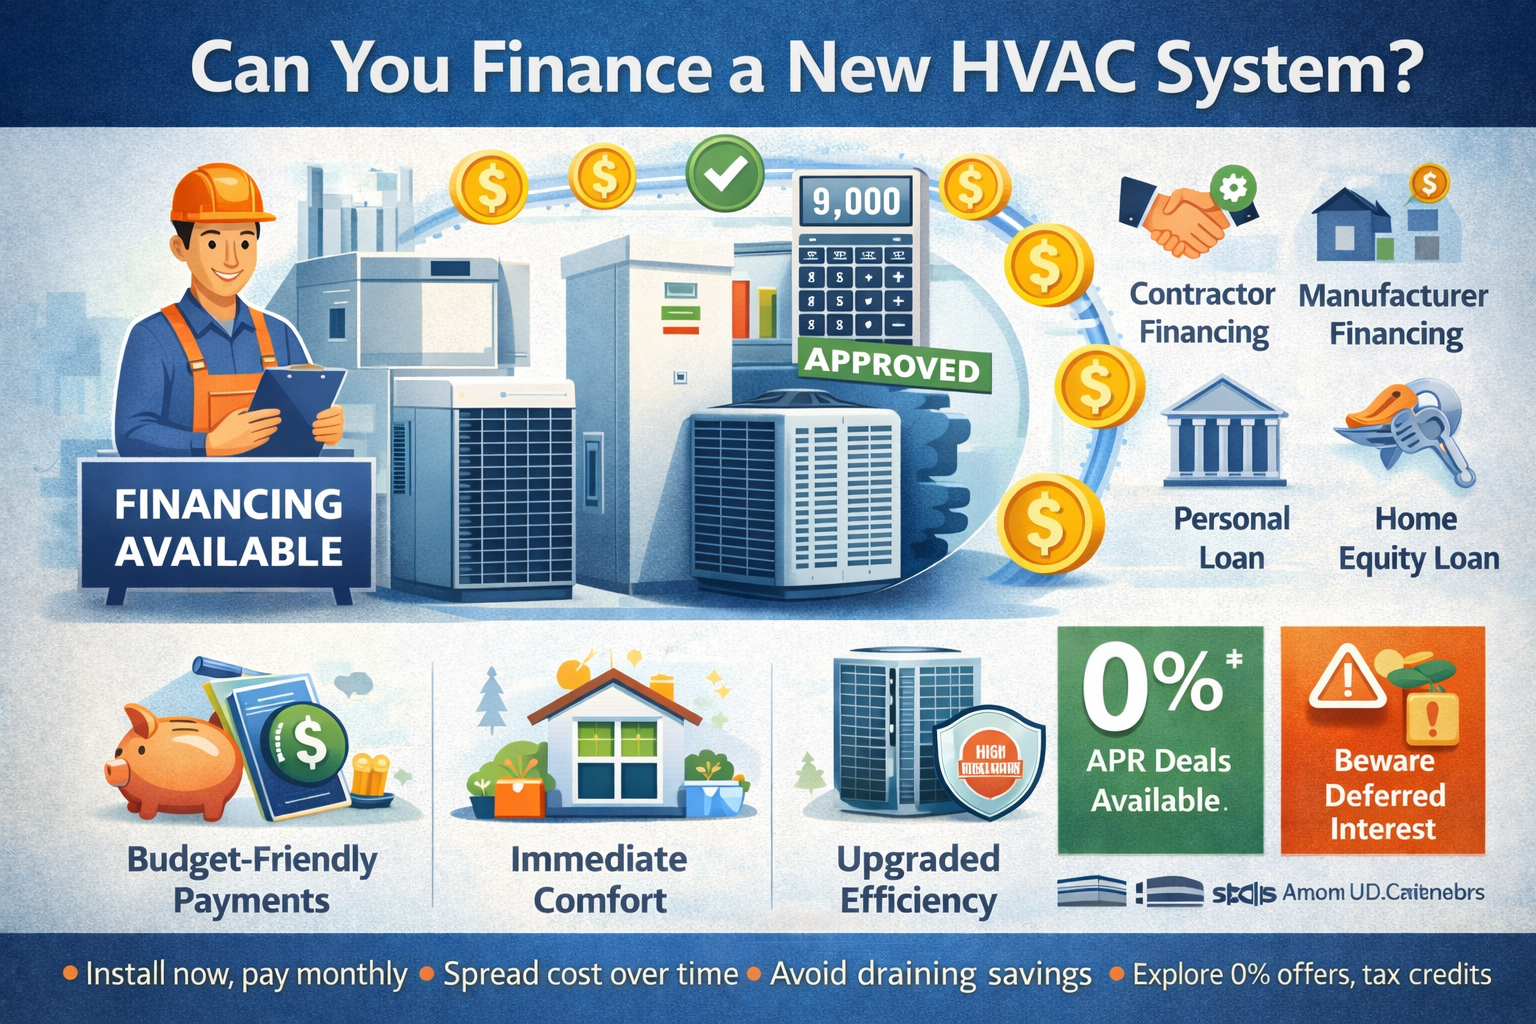
Most homeowners do not pay cash upfront. Instead, they use:
-
Contractor financing
-
Manufacturer programs
-
Personal loans
-
Home equity loans
-
Credit cards
-
Government-backed energy loans
Financing allows you to:
-
Install now
-
Pay monthly
-
Preserve emergency savings
-
Upgrade to higher-efficiency systems
3. What Does a New HVAC System Cost in 2026?
Understanding cost helps you choose the right financing plan.
Average HVAC System Costs (Installed)
| System Type | Average Cost |
|---|---|
| Central AC | $4,500 – $8,500 |
| Furnace | $3,000 – $7,000 |
| Heat Pump | $6,000 – $12,000 |
| Full HVAC Replacement | $8,000 – $15,000+ |
| Ductless Mini-Split | $5,000 – $10,000 |
Prices vary by:
-
Home size
-
Efficiency rating (SEER/HSPF)
-
Brand
-
Labor rates
-
Ductwork needs
4. Why Homeowners Choose HVAC Financing
Even homeowners with savings often finance.
Common Reasons:
-
Avoid draining emergency funds
-
Spread cost over 36–120 months
-
Access better equipment
-
Lock in fixed monthly payments
-
Take advantage of 0% APR offers
Financing turns a large, stressful expense into a manageable monthly bill.
5. How HVAC Financing Works (Step-by-Step)
Here’s what typically happens:
-
Get an HVAC estimate
-
Choose a financing option
-
Apply (online or in-home)
-
Credit check (soft or hard)
-
Approval decision (often same day)
-
Installation scheduled
-
Monthly payments begin
Many contractors handle financing on the spot, making the process seamless.
6. Common HVAC Financing Options
If you’re wondering can you finance a new HVAC system, the real question is how.
Primary Financing Options:
-
HVAC contractor financing
-
Manufacturer financing
-
Personal loans
-
Home equity loans / HELOCs
-
Credit cards
-
Government energy loans
Each option has different rates, terms, and approval requirements.
7. Manufacturer & Contractor Financing
HVAC Contractor Financing
Most HVAC companies partner with lenders.
Pros:
-
Easy approval
-
Fast processing
-
Promotional rates
-
No upfront payment
Cons:
-
Rates vary by credit
-
Penalties if promo expires
Manufacturer Financing
Brands like:
-
Trane
-
Lennox
-
Carrier
-
Goodman
Offer promotional financing through banks.
Popular offers include:
-
0% APR for 12–60 months
-
Deferred interest plans
8. Bank Loans vs Credit Cards vs HVAC Loans
| Option | Interest Rate | Best For |
|---|---|---|
| Personal Loan | 6–15% | Good credit |
| HVAC Loan | 5–12% | Mid-range credit |
| Credit Card | 18–29% | Short-term |
| HELOC | 6–9% | Homeowners |
Personal loans offer flexibility, while HVAC loans are purpose-built.
9. HVAC Financing With Bad Credit
Yes — you can finance a new HVAC system with bad credit.
Options for Low Credit Scores:
-
Subprime HVAC lenders
-
Co-signers
-
Secured loans
-
Higher APR plans
-
Shorter terms
Even scores below 600 can qualify, though rates will be higher.
10. 0% APR HVAC Financing: Is It Real?
Yes — but read the fine print.
Common 0% APR Structures:
-
12 months
-
18 months
-
36 months
-
Deferred interest
⚠️ If you miss payments or fail to pay off in time, interest is added retroactively.
11. Monthly Payment Examples
Example: $10,000 HVAC System
| Term | APR | Monthly Payment |
|---|---|---|
| 36 months | 0% | $278 |
| 60 months | 6% | $193 |
| 120 months | 9% | $127 |
Longer terms mean lower payments—but higher total cost.
12. HVAC Leasing vs Financing
Leasing is less common but exists.
Financing vs Leasing
| Feature | Financing | Leasing |
|---|---|---|
| Ownership | Yes | No |
| Monthly Cost | Medium | Low |
| Long-Term Cost | Lower | Higher |
| Tax Credits | Yes | No |
Financing is usually the smarter choice.
13. Benefits of Financing a New HVAC System
Key Advantages:
-
Immediate comfort
-
Budget-friendly payments
-
Energy savings
-
Access to high-efficiency units
-
Potential tax credits
New systems can cut energy bills by 20–40%.
14. Risks & Downsides to Consider
Financing isn’t risk-free.
Potential Downsides:
-
Interest costs
-
Credit score impact
-
Deferred interest traps
-
Long-term commitment
Always read the loan agreement carefully.
15. How to Qualify for HVAC Financing
Typical Requirements:
-
Proof of income
-
Credit score (varies)
-
Valid ID
-
Homeownership (sometimes)
Good credit opens better rates, but many programs are flexible.
16. Tips to Get Approved Faster
-
Apply with contractor partners
-
Improve credit utilization
-
Add a co-borrower
-
Choose shorter terms
-
Avoid multiple applications
17. Tax Credits, Rebates & Incentives
Financing + incentives = major savings.
Available Programs:
-
Federal HVAC tax credits
-
Energy-efficient rebates
-
Utility company incentives
-
State energy programs
High-efficiency heat pumps can qualify for thousands in credits.
18. Real-World HVAC Financing Examples
Example 1: Emergency Replacement
A family replaces a failed AC using 0% APR financing over 36 months.
Example 2: Energy Upgrade
Homeowner finances a heat pump and uses rebates to reduce total cost.
Example 3: Bad Credit Approval
Borrower qualifies through a subprime HVAC lender with a co-signer.
19. FAQs – People Also Ask (Schema Ready)
Can you finance a new HVAC system with no money down?
Yes. Many contractors offer zero-down financing options.
What credit score is needed for HVAC financing?
Some lenders approve scores as low as 580, though higher scores get better rates.
Is it better to finance or pay cash for HVAC?
Financing is better if you get low interest or preserve savings.
How long can you finance an HVAC system?
Terms typically range from 12 to 120 months.
Does HVAC financing hurt your credit?
Only if payments are missed. On-time payments can improve credit.
20. Conclusion & Actionable Takeaways
So, can you finance a new HVAC system?
Absolutely — and for most homeowners, it’s the smartest option.
Key Takeaways:
-
HVAC systems are expensive but financeable
-
Multiple loan options exist for all credit levels
-
0% APR deals can save thousands
-
Always compare terms and total cost
-
Use rebates and tax credits to reduce expenses
Action Steps:
-
Get multiple HVAC quotes
-
Ask about financing before choosing a contractor
-
Compare APR, term, and total cost
-
Check eligibility for rebates
-
Choose comfort without financial stress
A broken HVAC shouldn’t break your budget — financing makes comfort affordable.